

Most used cars are now advertised with a monthly figure next to the price, so it's natural to shop by what you can pay each month. But what does £200, £300 or £400 a month buy in a used car, and what does the loan cost on top? Carplus turned each payment into the cars it buys across 41,284 used-car ads on two large UK dealer websites.
Key findings
- £200 a month buys a £9,140 car, typically 8 years old with 54,000 miles. Only 13% of the cars for sale cost this or less.
- £300 a month buys a £13,700 car, typically 4 years old with 32,000 miles. 39% of cars cost this or less.
- £400 a month buys an £18,270 car, typically 3 years old with 24,000 miles. Two in three cars cost this or less.
- Need an automatic? Budget £300 or more. Only 18% of the cars at £200 a month are automatics, against 69% at £400.
- The loan adds about a third. Over 5 years, £300 a month adds up to £18,000 for a £13,700 car.
How much car does each monthly payment buy?
Each monthly payment matches one car price on the finance quote the ads show, so £300 a month buys a £13,700 car that's typically 4 years old. That works because every ad in the data shows the same quote, which is hire purchase (HP) over 5 years with no deposit at 11.9% APR.
With HP, you pay fixed monthly instalments and own the car once the final payment is made. APR (annual percentage rate) is the yearly cost of borrowing, including interest and any fees.
| Monthly payment | Car price | Typical age | Typical mileage | Cars for sale at this price or less |
|---|---|---|---|---|
| £200 | £9,136 | 8 years | 54,000 | 13% |
| £300 | £13,704 | 4 years | 32,000 | 39% |
| £400 | £18,272 | 3 years | 24,000 | 66% |
Your own rate may be higher or lower than the one in the ads, because it depends on your credit history and the lender. So treat these prices as what the advertised quote buys, not what you'll be offered.
Why the first extra £100 a month buys the most
The first extra £100 a month buys the most, because moving from £200 to £300 takes about 4 years off the typical car. The next £100 takes off only about 1 more year.
That first step widens your choice, too. About 3 times as many cars for sale cost £300 a month or less as cost £200.
You can see the gap within a single model. At £200 a month, the typical Nissan Qashqai is 8 years old with 65,000 miles. At £400, it's 3 years old with 19,000.
Which models can you get at each payment?
Popular models turn up at every payment, but at very different ages. These are typical examples, with the typical age and mileage of each model at that payment:
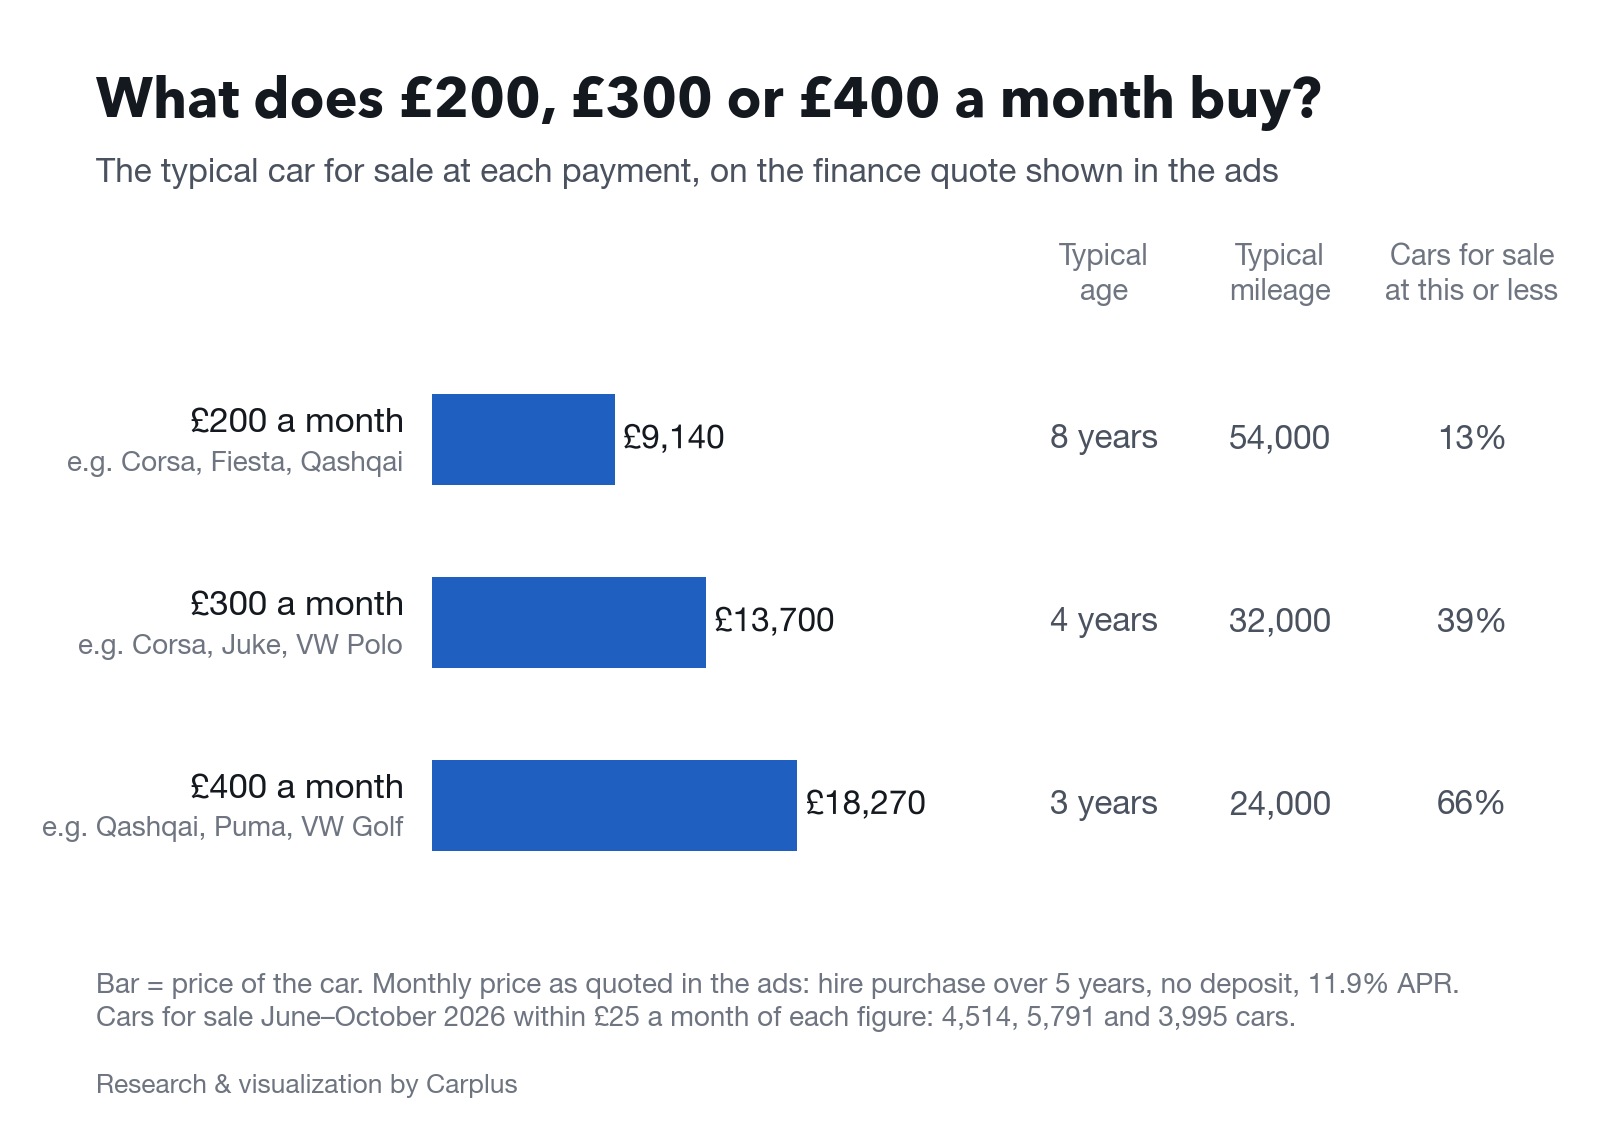
- £200 a month: a Vauxhall Corsa (6 years, 39,000 miles), Ford Fiesta (7 years, 46,000), Nissan Qashqai (8 years, 65,000), Ford Focus (7 years, 65,000) or Fiat 500 (4 years, 31,000).
- £300 a month: a Vauxhall Corsa (3 years, 15,000 miles), Nissan Juke (3 years, 21,000), VW Polo (5 years, 34,000), Vauxhall Mokka (3 years, 22,000) or MG ZS (3 years, 19,000).
- £400 a month: a Ford Puma (3 years, 14,000 miles), Nissan Qashqai (3 years, 19,000), VW Golf (4 years, 27,000), Hyundai Tucson (4 years, 28,000) or a Vauxhall Mokka (1 year, 9,000).
What kind of car does each budget buy?
Each monthly budget buys a different size of car, with small cars leading at £200 a month and small or compact SUVs taking over from £300. At £200, city cars and superminis make up 39% of what's for sale. Small or compact SUVs aren't far behind, at 33%.
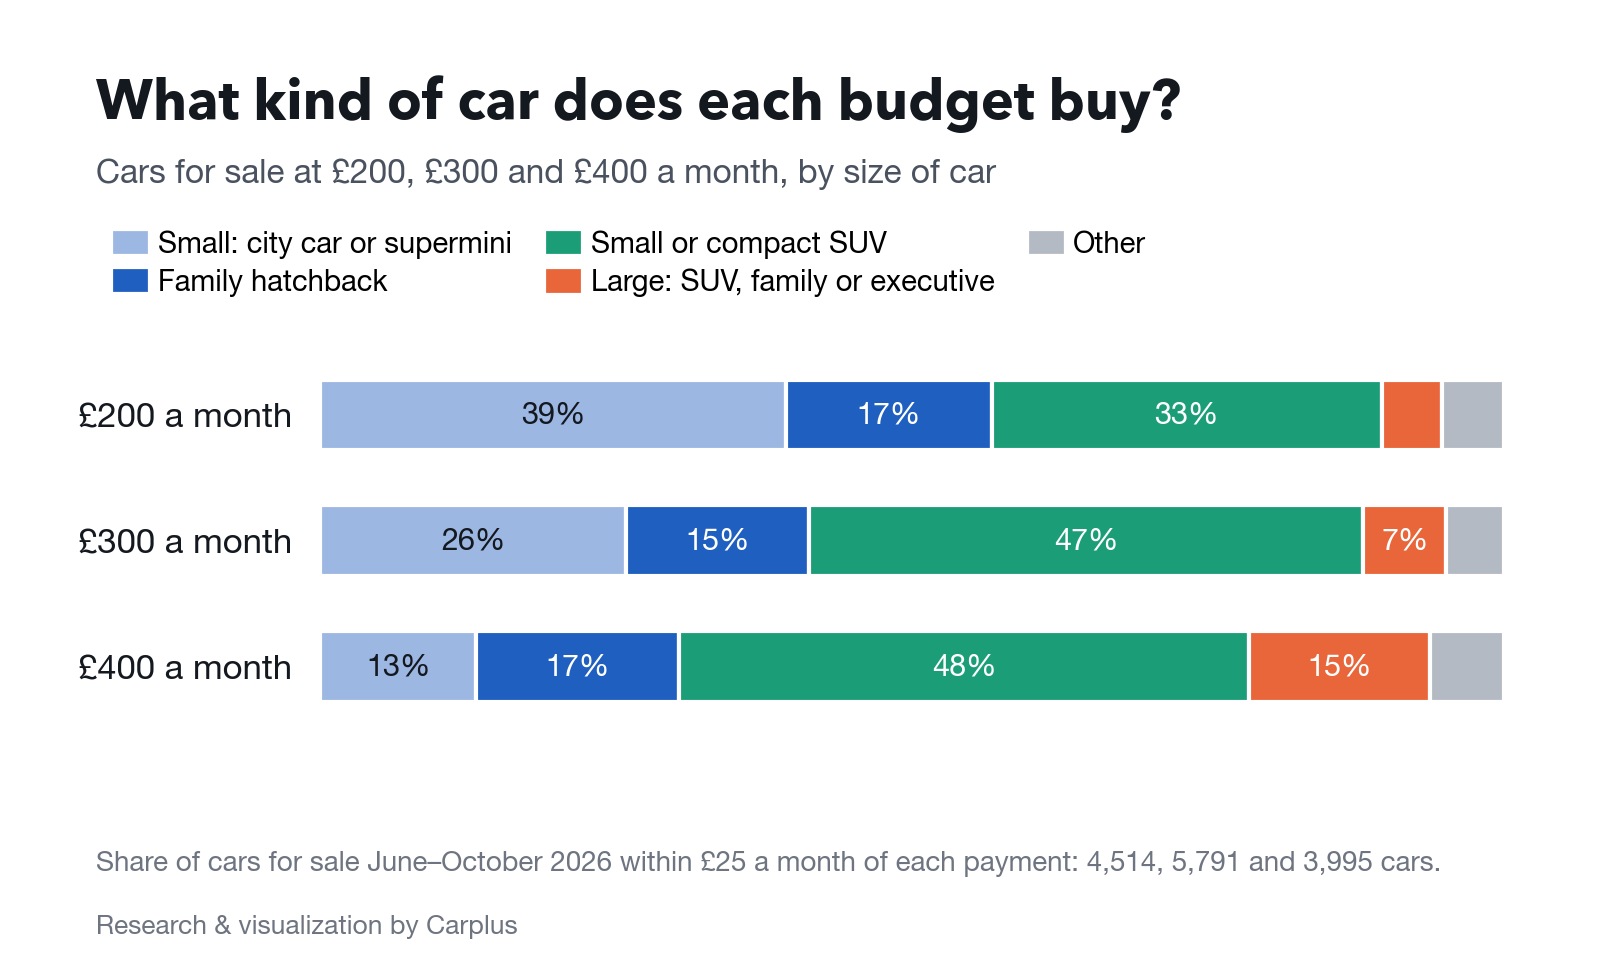
From £300 a month, those SUVs pull ahead and make up almost half of what's on offer. Spend £400 and large cars (large SUVs and family or executive cars) appear 3 times as often as at £200, at 15% of the cars for sale.
Family hatchbacks hold steady whatever you pay. They're about one car in six at every payment.
Will you get an automatic, a hybrid or a premium brand?
An automatic, a hybrid or a premium brand gets more likely the more you pay each month, while a diesel gets less likely. The gearbox swings the most, from 18% automatics at £200 a month to 69% at £400.
Below £300 a month, most cars are manuals. If you only drive an automatic, budget £300 or more, where 39% of the cars are automatics. Across all cars for sale, the share is 53%.
Hybrids follow a similar path. They're 4% of the cars at £200 a month, and from £300 they're as common as across all cars for sale, at about 15%.
Diesel runs the other way. At £200 a month, 26% of the cars are diesels, more than the 22% across all cars, and the share drops to 17% to 19% from £300.
Premium brands mostly arrive at £400 a month. At that payment you get the market's usual share of Audi, BMW and Mercedes (29%), but below it there are far fewer.
What does each payment buy in an electric car?
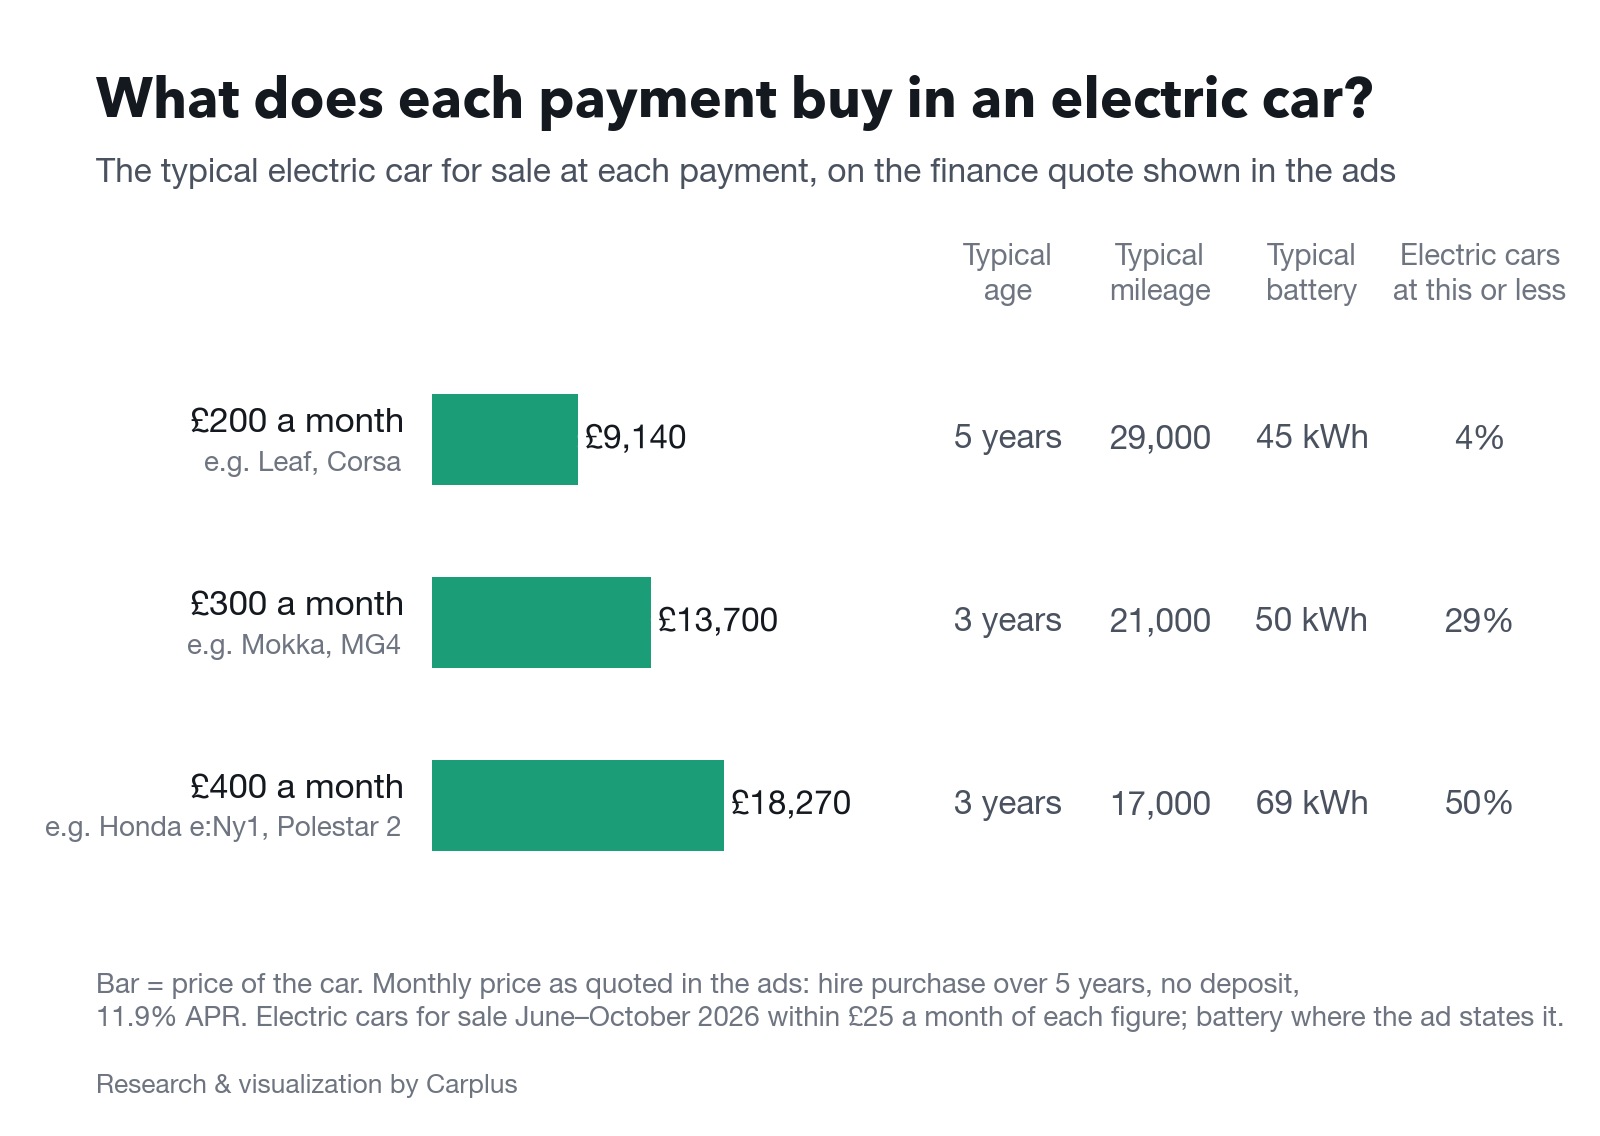
An electric car at £200 a month is typically 5 years old with 29,000 miles, about 3 years younger than the typical car overall at that payment. Electric cars lose value faster in their first years, so they reach these prices sooner. Carplus's analysis of which used cars hold their value shows how that early drop works.
Choice is the limit. Only 4% of the 1,576 electric cars for sale cost £200 a month or less, and half of them cost more than £18,100, about £400 a month. Across all payments, electric cars make up just 3% to 4% of what's on offer.
Battery size grows with the budget. A battery's size is measured in kWh (kilowatt-hours), and a bigger battery usually means a longer range between charges.
- £200 a month: a 5-year-old with 29,000 miles and a 45 kWh battery, such as a Nissan Leaf, Vauxhall Corsa Electric, Renault Zoe, MG ZS EV or Fiat 500e. Only 5% have a battery of 60 kWh or more.
- £300 a month: a 3-year-old with 21,000 miles and a 50 kWh battery, such as a Vauxhall Mokka Electric, MG4, VW ID.3 or Peugeot e-2008. A quarter have a battery of 60 kWh or more.
- £400 a month: a 3-year-old with 17,000 miles and a 69 kWh battery, such as a Honda e:Ny1, Polestar 2, Hyundai Kona Electric or Jaguar I-Pace. 72% have a battery of 60 kWh or more.
How much does the loan add to the price?
On the quote in the ads, the loan adds about a third to the price of the car over 5 years. You'll see it in the total you pay back:
| Monthly payment | Car price | Total paid over 5 years | Interest |
|---|---|---|---|
| £200 | £9,136 | £12,000 | £2,864 |
| £300 | £13,704 | £18,000 | £4,296 |
| £400 | £18,272 | £24,000 | £5,728 |
Finance is always subject to status, so the rate you're offered depends on your credit history and the lender. Dealers who name a rate in their ads (about 1 ad in 100) mostly advertise finance from 7.9% to 12.9% APR. Those are the lowest rates on offer, not what everyone gets.
How can the same monthly payment buy more car?
A deposit makes the same monthly payment buy the most extra car, while a lower rate adds a little. A shorter loan buys less car but costs you less in interest. Here's what £300 a month buys in each case:
| £300 a month | Car price | What changes |
|---|---|---|
| Standard quote (5 years, 11.9% APR, no deposit) | £13,700 | Interest of about £4,300 |
| Lower rate (7.9% APR) | £14,930 | About £1,220 more car |
| 20% deposit | £17,130 | You need £3,430 up front |
| Shorter loan (4 years) | £11,540 | Interest falls to about £2,860 |
So if you can put money down, you'll stretch a monthly budget further with a deposit than with any other change.
Which monthly budget should you aim for?
For most buyers, £300 a month is the budget to aim for, because the step up from £200 takes the typical used car from 8 years old to 4. Going on to £400 takes off only about another year.
Your needs can change that. Want an automatic, a hybrid or a premium brand? £400 a month is where they become common. Happy with a small manual car? £200 a month works, as long as you're comfortable with an 8-year-old car and around 54,000 miles. Thinking of going electric? £300 a month buys a 3-year-old with a mid-sized battery, and £400 a bigger one.
Before you settle on a monthly figure, turn it into a price. On the standard quote, every £100 a month over 5 years buys about £4,570 of car.
In Part 4, Carplus looks at which features make a used car more expensive, and which of them hold their value when you sell.
Found a car you like? Check your own rate – we use a soft search, so there's no impact on your credit score.
Table of Contents